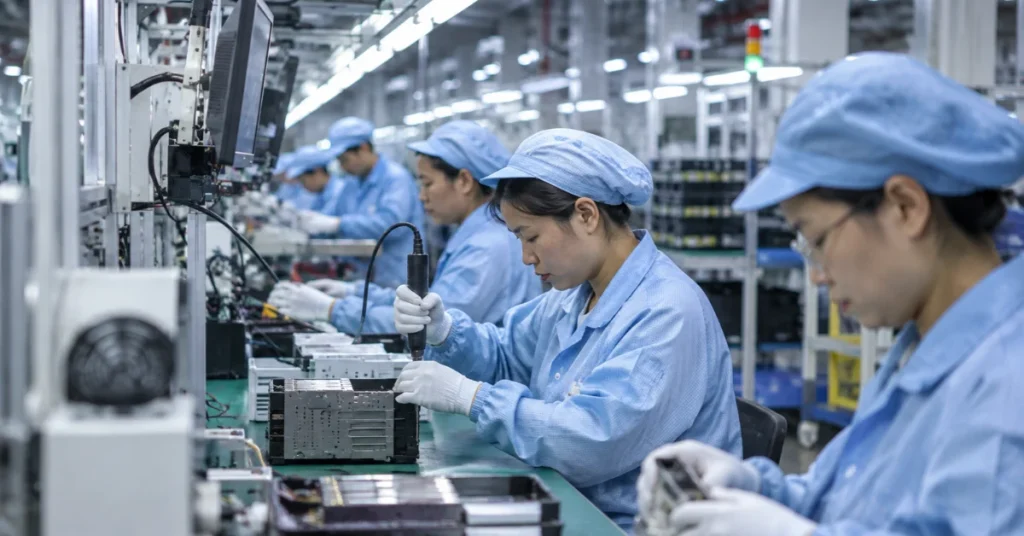
October 31, 2026: China’s manufacturing activity returned to contraction in October as factory production and new orders weakened, reversing a brief recovery in September. The official manufacturing Purchasing Managers’ Index (PMI) fell to 49.3 from 50.1 in the previous month, according to data released on Saturday by the National Bureau of Statistics (NBS).
The decline signals renewed pressure on the world’s second-largest economy at the beginning of the final quarter of 2026. New manufacturing orders and export orders weakened, while construction activity also moved into contraction. The figures point to softer demand within China and raise questions about the outlook for global manufacturers, commodity suppliers and international trade.
The manufacturing PMI is compiled from monthly surveys of purchasing managers and provides an early indication of business conditions. A reading above 50 signals expansion compared with the previous month, while a reading below 50 indicates contraction. October marked the third month of manufacturing contraction in four months, following readings of 49.2 in July, 49.8 in August and 50.1 in September.
The index does not measure the percentage change in actual factory production. Instead, it reflects changes in reported business conditions, including production, new orders, employment, inventories and delivery times.
The October survey showed that the manufacturing production index fell to 49.8 from 51.7 in September, moving below the expansion threshold. The new orders index declined to 49.4 from 50.5, indicating weaker demand for manufactured goods.
New export orders dropped to 48.7 from 50.0, suggesting that conditions for overseas orders had also deteriorated. The purchasing activity index fell to 48.9 from 51.0, adding to evidence of weaker factory activity.
The National Bureau of Statistics attributed part of the slowdown to the timing of demand around China’s National Day holiday and uncertainty in the international environment.
Huo Lihui, chief statistician at the National Bureau of Statistics’ Service Industry Survey Centre, explained in an official commentary published on the bureau’s website on October 31 that manufacturing activity had weakened partly because some demand was brought forward ahead of the National Day holiday. She also cited a complex and changing international environment as a factor behind the slowdown.
The explanation suggests that the timing of orders contributed to October’s deterioration. However, the simultaneous declines in production, domestic orders and export orders indicate that manufacturers entered the final quarter with weaker business conditions than in September.
The broader economic survey showed that the slowdown extended beyond manufacturing. China’s non-manufacturing business activity index, covering services and construction, fell to 49.7 from 50.2, moving below the expansion threshold.
Construction recorded a particularly sharp decline. Its business activity index dropped to 48.0 from 50.3, while the construction new orders index fell to 40.0 from 45.7. Both readings indicate weaker conditions, particularly in demand for new construction work.
The findings follow a difficult third quarter for the industry. Official national accounts released earlier in October showed that construction’s real value added declined by 4.4% year on year between July and September.
The construction slowdown matters beyond property developers and building companies. Construction and infrastructure projects influence demand for steel, cement, copper and other industrial materials. If weaker activity persists, it could affect suppliers of these products, although the October survey does not establish how much actual commodity consumption has changed.
Services performed better than construction but also lost momentum. The services business activity index edged down to 50.0 from 50.2, indicating broadly unchanged conditions rather than clear expansion.
The statistics bureau reported relatively strong activity in water transportation, postal services, and internet-related information technology services. Activity linked to holiday travel and consumption also improved in some service industries, while financial services weakened.
The composite PMI output index, which reflects activity across manufacturing and non-manufacturing industries, declined to 49.7 from 50.7. Its movement below 50 provides further evidence that overall business conditions deteriorated in October.
Despite the broader manufacturing contraction, some advanced industrial sectors continued to expand. High-technology manufacturing recorded a PMI of 51.3, while equipment manufacturing stood at 50.6.
Huo’s official commentary highlighted comparatively strong production and new order conditions in railway, shipbuilding and aerospace equipment manufacturing, as well as computer, communications and electronic equipment manufacturing. Both production and new orders indices for these industries were at or above 53.0.
Other industries faced weaker demand. Production and new orders readings were below 50 in textiles, non-metallic mineral products and non-ferrous metal processing. Consumer goods manufacturing recorded a PMI of 48.8, while energy-intensive industries stood at 47.3.
These differences show that China’s manufacturing slowdown was uneven. Parts of advanced manufacturing remained in expansion even as several traditional industries experienced weaker business conditions.
The survey also revealed differences between manufacturers of different sizes. Large companies recorded a PMI of 50.2, remaining slightly above the expansion threshold, while medium-sized manufacturers registered 48.4 and small manufacturers stood at 47.5.
Both medium and small manufacturers experienced weaker conditions than in September, suggesting that the broader slowdown was more pronounced among smaller businesses.
Price indicators presented a mixed picture. The manufacturing raw material purchase price index fell to 56.8 from 60.8, while the factory-gate price index declined to 51.7 from 54.0.
Both indices remained above 50, indicating that manufacturers were still reporting rising prices overall, but with less widespread upward pressure than in September. The statistics bureau partly attributed the easing to lower prices for some non-ferrous metal commodities, while noting continued elevated price pressures in petroleum processing and certain chemical-related industries.
For international markets, the October figures matter because China is a major buyer of industrial commodities and an important producer of manufactured goods and components used worldwide.
Weaker construction activity and factory purchasing could reduce the momentum of demand for some imported raw materials if the slowdown continues. At the same time, expansion in high-technology and equipment manufacturing suggests that demand for products and materials used in those industries may remain more resilient.
However, the PMI figures alone cannot establish whether China’s actual imports of iron ore, copper, crude oil or other commodities declined in October. They also do not prove that global commodity prices will fall. Such conclusions require separate evidence from trade data, industrial output and market prices.
The decline in new export orders has implications for international trade. China’s manufacturers supply goods and components to markets around the world, making overseas order conditions an important indicator of potential changes in demand.
October’s reading of 48.7 suggests weaker conditions for new export business, but it does not measure the actual value or volume of goods shipped during the month. Official trade figures will be needed to establish whether the deterioration was reflected in exports.
The slowdown follows a period of slightly stronger year-on-year economic growth. Official figures showed that China’s gross domestic product expanded by 4.5% in July–September 2026 compared with the same quarter a year earlier, following year-on-year growth of 4.3% in April–June. GDP grew by 4.6% across the first nine months of 2026 compared with the corresponding period of 2025.
The October PMI figures therefore suggest a weaker start to the final quarter despite the improvement in third-quarter growth. They do not, by themselves, establish how much the economy will expand over the full quarter or year.
Upcoming industrial production, retail sales and trade figures will provide a clearer indication of whether the weaker conditions reported by purchasing managers are also reflected in actual factory output, domestic spending and international shipments.
Read also : India moves closer to restoring NavIC navigation services after successful NVS-03 launch
Read also : America’s emergency oil stockpile is shrinking: How new exchange deals aim to replenish it